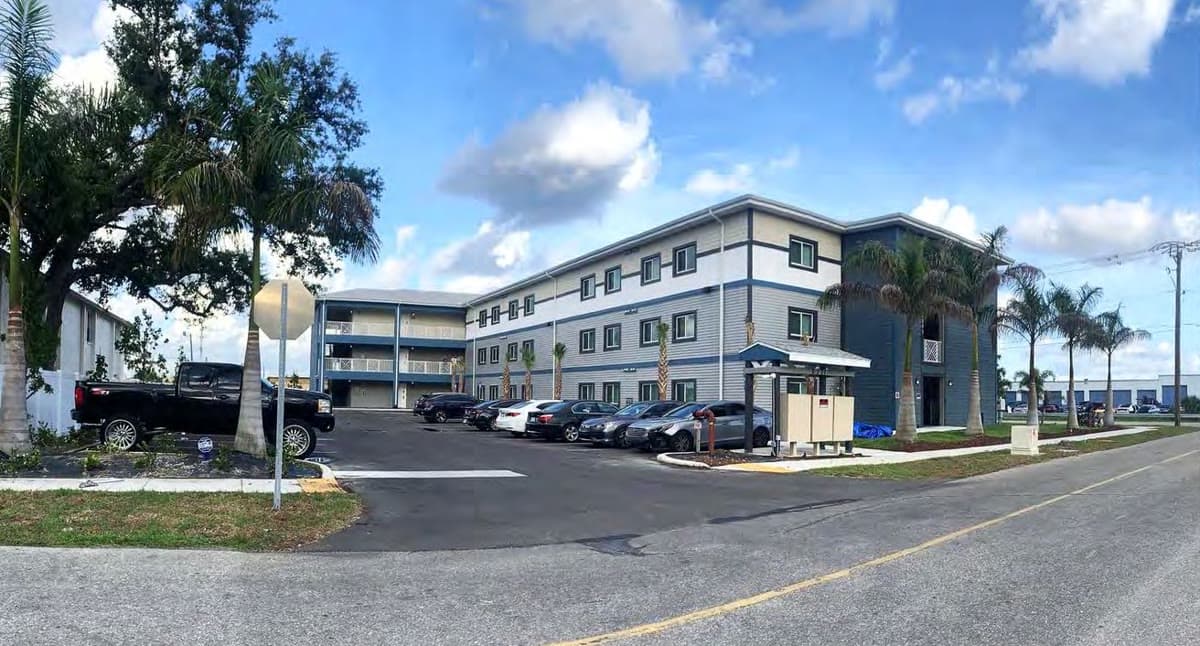
DSCR / Multifamily
Multifamily DSCR Loans
Qualify a 2–4 unit or 5+ unit rental property on its rent roll — not your tax returns, W-2s, or personal debt-to-income.
What Is a Multifamily DSCR Loan?
A multifamily DSCR loan is a Debt Service Coverage Ratio loan sized against a multi-unit property's rental income instead of the borrower's personal income. If the building's rent covers its own mortgage payment — principal, interest, taxes, and insurance — it qualifies, regardless of what shows up on a tax return. That makes DSCR the standard financing tool for investors who own property through an LLC, self-employed sponsors whose tax returns understate cash flow, and anyone scaling past the number of conventional loans a personal DTI can support.
“Multifamily DSCR” covers two distinct property types with different underwriting mechanics. 2–4 unit residential properties (duplexes, triplexes, quads) qualify almost identically to a single-family DSCR rental — same appraisal process, same underwriting, same 30-year fixed programs. 5+ unit multifamily is treated as small commercial: a commercial income-approach appraisal, underwriting against the property's net operating income rather than a single-family rent comp, and stricter entity and reserve requirements at that size. 818 lends on both.
How Multifamily DSCR Qualification Works
DSCR = Gross Rental Income ÷ Monthly PITI. On a 2–4 unit property, we total the actual or market rent across every unit. On a 5+ unit building, we underwrite against net operating income — gross rent less a vacancy factor and operating expenses — because that's how a commercial appraiser will size the property's value.
Example: 8-Unit Building
This deal works. Green light.
Rate & Term Ranges
General guardrails, not a quote — your exact rate depends on credit, DSCR, LTV, and unit count.
2–4 Unit Residential
Term: 30-year fixed, IO options
Max LTV: Up to 80% LTV
Priced close to a 1-unit DSCR loan; the most program options.
5–20 Unit Multifamily
Term: 30-year fixed or 5–10yr fixed with balloon
Max LTV: Up to 80% LTV
Priced with a modest premium over 2–4 unit; fewer program options in this band.
5+ Unit Commercial vs. 2–4 Unit Residential
Same DSCR concept, different underwriting file.
2–4 Unit Properties
- Residential-style appraisal with comparable rent survey
- Qualifies on gross unit rent, actual or market
- Most program options, fastest close (14–21 days)
- Treated the same as a 1-unit DSCR file operationally
5+ Unit Multifamily
- Commercial income-approach appraisal (longer turn time)
- Qualifies on net operating income, not gross rent
- Fewer program options; entity and reserve requirements are stricter
- Above ~20 units, most deals route to agency or bridge instead of DSCR — see our full multifamily financing page for those programs.
The numbers behind the relationship.
Trailing 12 months · drawn from cleared funded deals
- DSCR25%
- Fix & Flip17%
- Multifamily17%
- STR8%
- Bridge17%
- Construction8%
- Structured8%
Instant Property Valuation Pre-Check
When you submit a deal, our AI appraisal engine automatically runs a conservative, lender-grade valuation analysis. You get a value range, confidence score, and risk flags — before underwriting even starts.
As-Is & Stabilized Value Ranges
Low / mid / high estimates using income, sales comparison, and cost approaches.
Confidence Score & Risk Flags
Know where your deal stands before submission. Conservative, lender-first output.
Credit Committee Notes
Internal-grade analysis notes you can use when packaging the deal for lenders.
As-Is Value Range
Key Metrics
NOI Annual
$38,400
Implied Cap Rate
8.4%
Price / SqFt
$212
Methods Used
Income + Comps
Risk Flags (2)
Limited recent comps within 0.5 mi • Vacancy data from 2024 Q3
Common questions.
Can I get a DSCR loan on a multifamily property?
Yes. 818 underwrites DSCR loans on 2–4 unit residential properties and 5–20 unit multifamily assets using the same core mechanic: the property’s rent has to cover the mortgage payment. Above roughly 20 units, most deals shift to agency, bridge, or CMBS execution instead of DSCR.
Is a multifamily DSCR loan the same as a DSCR loan on a single-family rental?
The math is identical — DSCR = gross rental income ÷ PITI — but multifamily underwriting leans harder on the rent roll and, on 5+ unit deals, on net operating income rather than a single lease. Reserve requirements and appraisal methodology (income approach) also differ from a 1-unit file.
What DSCR do I need on a multifamily property?
1.20× or higher gets our best pricing. 1.00–1.19× still qualifies with a modest rate adjustment. Below 1.00×, expect a lower max LTV, stronger credit, and more reserves, especially on 5+ unit deals.
Do 5+ unit multifamily DSCR loans require a commercial appraisal?
Yes. 2–4 unit properties are typically appraised like residential investment property. 5+ unit buildings require an income-approach commercial appraisal, which takes longer and weighs the rent roll and expense ratio directly into the value opinion.
What is the maximum LTV on a multifamily DSCR loan?
Up to 80% LTV on both 2–4 unit properties and 5–20 unit buildings. These are general guardrails, not a quote; the exact figure depends on credit, DSCR, and unit count.
How many units can a DSCR loan cover?
DSCR programs cover 2–4 unit residential properties and 5–20 unit multifamily buildings. Above roughly 20 units, most deals are better served by agency, bridge, or CMBS execution, which are covered on the apartment and multifamily loans page.
How long does a multifamily DSCR loan take to close?
2–4 unit files close fastest, typically 14–21 days. 5+ unit files take longer because they need an income-approach commercial appraisal. These are typical timelines, not a commitment.
Have a Deal Right Now?
Submit your multifamily scenario. Our AI Scenario Desk reads the rent roll and gives you a real DSCR, LTV, and next-step read.
Prefer to read the full DSCR framework first? See the 2026 DSCR Investor Playbook →